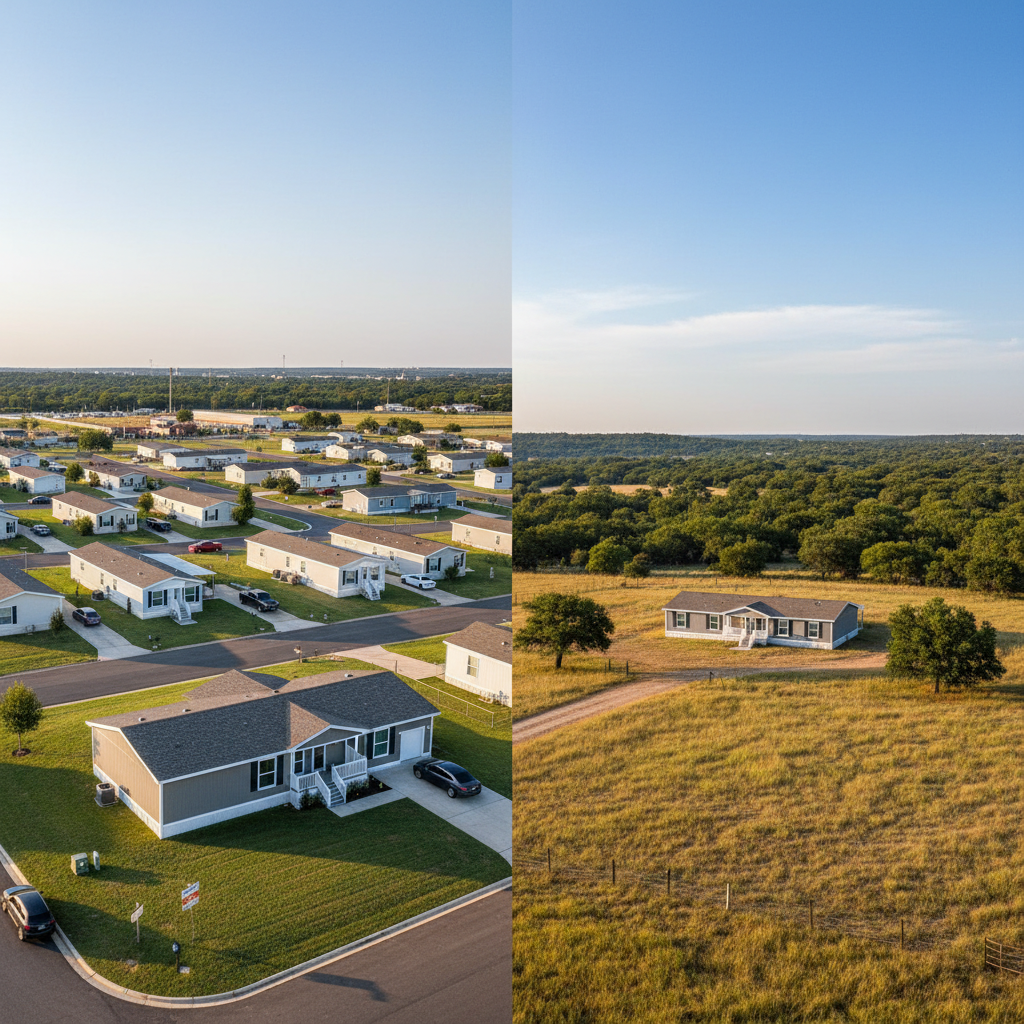
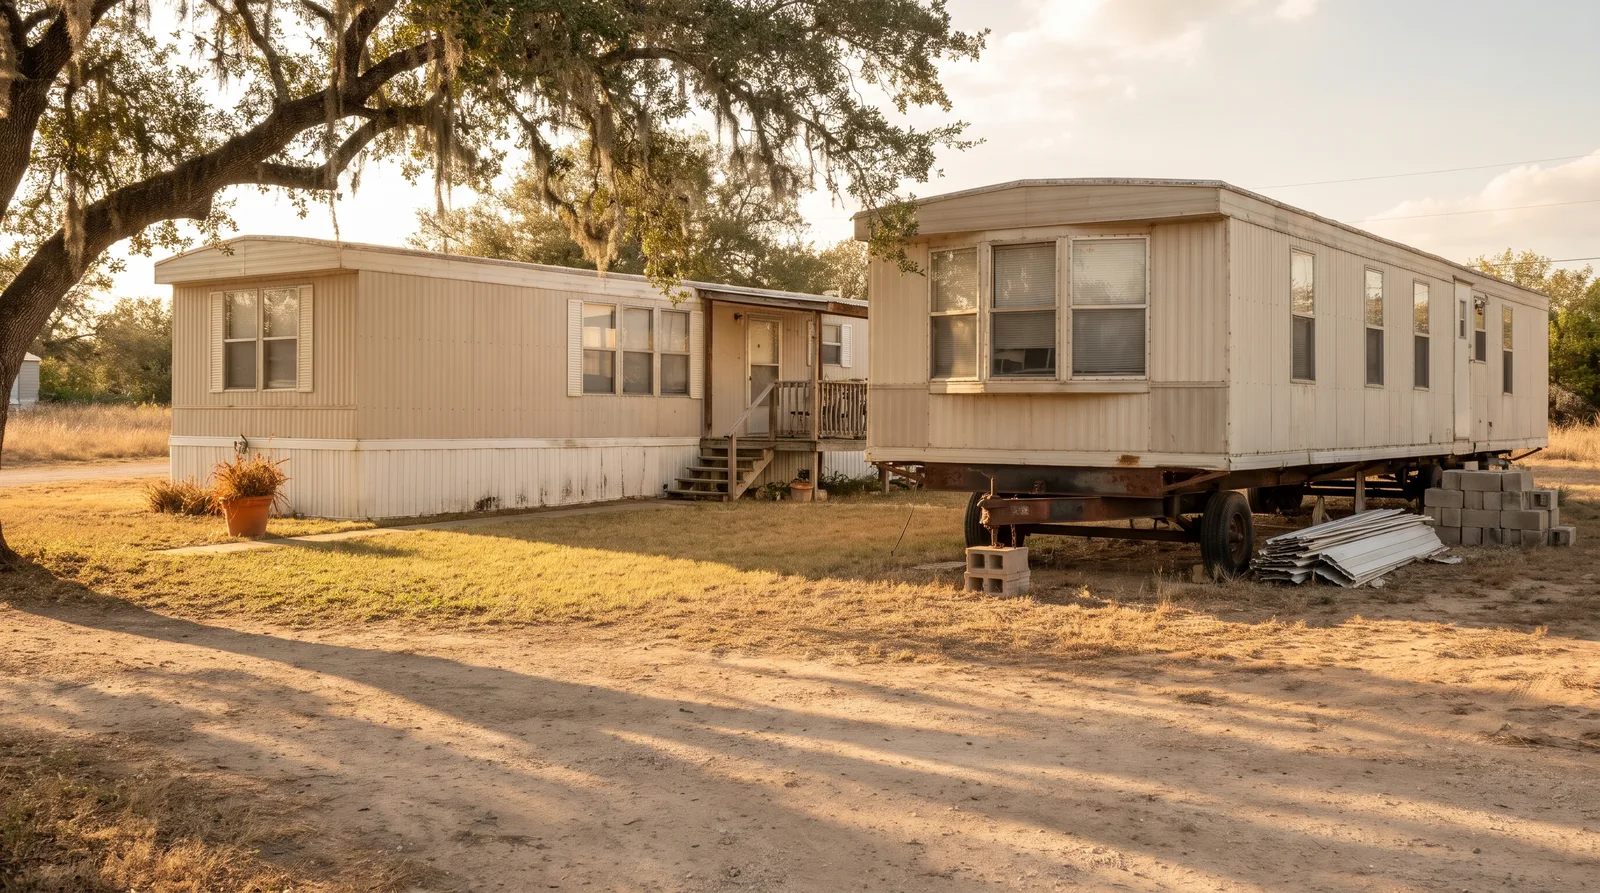
It mostly comes down to whether the home stays where it is. On our listings, homes that can stay in their community are the ones that carry a line offering lenders who specialize in manufactured homes, and a lender who does mobile homes may finance them. Homes that must be moved usually sell for cash, so check which kind a home is before you set your heart on it.
Two things to check on the listing
First, the label. Every home on our listings page is marked In Community, Must Be Moved or Land Included.
Second, read to the end of the description and look for this line: NEED FINANCING? We can provide lenders who specialize in Manufactured Homes! Our listing rules allow that line only on homes that can stay in a community or that sit on the owner's land. When a home must be moved, the rules leave financing out of the description altogether.
Here's how that looked on the homes we had listed when we wrote this, 82 in all:
| Label | Homes | With a financing line |
|---|---|---|
| In Community | 61 | 36 |
| Must Be Moved | 20 | 0 |
| Land Included | 1 | 0 |
One Must Be Moved listing says "Cash sale only." The others don't mention financing at all. Notice too that 25 In Community listings had no financing line. If the home you like is one of them, ask us whether it can be financed before you assume either way.
Homes that stay in their community
You buy the house and rent the lot, and a lender that finances manufactured homes in communities can lend on the house alone. Our guide to chattel loans explains how a loan on a home without its land works.
Some buyers have heard the opposite. One told us:
"they won't finance if its in a community"
On our listings, these are the homes we mark for financing. The lender still decides whether to lend to you, and the community still has to approve you as a resident before you buy. You can use a lender we refer you to, or your own, as long as it finances mobile homes in communities.
Homes that must be moved
Plan on paying cash. Our listings don't offer financing on these homes, and when a buyer asked us about a loan for one, our team said a lender won't finance a home that still has to be moved. You'll also pay to have the home moved and set up on your land, on top of the price.
If you'd still like to talk through your plans with a lender, tell us and we'll put you in touch.
Homes that come with land
These are rare on our site. On the homes we had listed when we wrote this, 1 out of 82 came with its land, and it was listed for cash. Our team has told buyers we don't know a lender who finances a home and its land together, so ask us before you count on a loan for one.
Ask before you drive out
In the past year, 16 buyers asked us whether a home could be financed or was cash only. Four gave it as a reason not to go ahead, and one felt misled:
"I felt like it was a bait and switch and didn't like that."
One of the first things we'll ask you is whether you're paying cash or financing, so we can send you homes that fit. If you're financing, ask "Can this one be financed?" about any home before you go to see it, and we'll tell you what we know about that listing.
If you're paying cash, every label is open to you. We'll ask you for proof of funds, and if the home is staying in a community, you'll still need the community's approval.
Tell us how you're paying
Say whether you're paying cash or financing and which area you want. We'll send you homes that fit, and if you need a loan, we can connect you with lenders who finance mobile homes.
Tell Us What You're Looking ForPrices, lot rents and community rules change, so check each listing for its current details. This article is for general education only. We aren't lawyers, accountants or financial advisors, and nothing here is legal, tax or financial advice of any kind.